


With the new methodology for calculating the DUB SME multiples introduced last year, the e-commerce and retail sector has come into particular focus. This sector showed the widest range of multiples, which ranged from 4 to 10 times EBIT.
The e-commerce and retail sector is highly heterogeneous in several respects, a fact that has now manifested itself in significant differences in pricing during the years marked by the COVID-19 pandemic. This makes it more difficult for entrepreneurs and consultants to interpret and apply the multiples to a specific company. This article will therefore examine which factors require particular consideration when valuing a company in this segment.
In particular, the aim is to counteract the risk of overestimation on the seller’s side, as a (significantly) inflated expectation of the minimum price leads to serious offers being rejected as too low, which often results in a failed sale. The effect of finding it nearly impossible to mentally let go of a number once it has been heard is known in marketing as the “anchor” effect. This phenomenon can already be observed in two other contexts in the field of business acquisitions: on the one hand, when valuing a business using the tax-related but unrealistic multiplier of 13.75 pursuant to the German Valuation Act (BewG), and, on the other hand, through unscrupulous advisors and brokers who confirm nearly every price expectation expressed by potential clients—but only to secure the sales mandate and the fixed monthly retainer typically associated with it.
Companies in the e-commerce and retail sector can currently be distinguished primarily by the following characteristics:
• eCommerce vs. Retail
• Retail vs. Wholesale
• Sector vs. Industry
• Crisis winners vs. crisis losers
e-commerce vs. retail
The name of the group itself already provides the first clue that it encompasses at least two segments. In both areas, the sale of goods—that is, products not manufactured in-house—is the core of the business model. However, while companies in traditional retail sectors primarily operate brick-and-mortar stores—which require leased space, staff, and capital for warehouses and sales areas—e-commerce companies are generally purely virtual and often have a very different cost structure.
Because many fixed costs are eliminated, the break-even point is reached sooner, resulting in a lower risk of loss. This, in turn, allows for a lower margin, which leads to lower prices and improved competitiveness. The potential for scalability plays a major role in valuation here.
In terms of valuation multiples, this means that e-commerce companies tend to command higher multiples, while brick-and-mortar retailers tend to have lower multiples.
Winners vs. Losers of the Crisis
During the COVID-19 pandemic, companies in these two sectors were also affected very differently by closures. While many—not all!—retailers had to temporarily close and thus suffered a 100% loss in revenue, e-commerce companies were not affected by such restrictions.
One sector’s disadvantage is the other’s advantage—since certain needs could no longer be met in brick-and-mortar stores due to the restrictions, the corresponding purchases were made online. The growth of online retail makes this very clear.
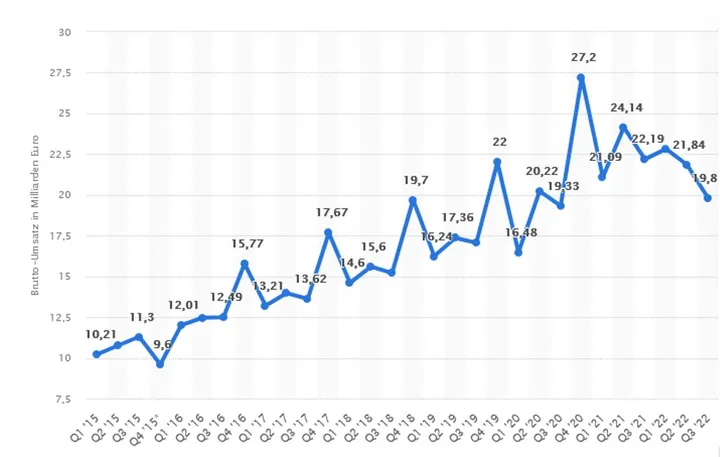 Source: Gross turnover in online retail (B2C-E) in Germany from the first quarter of 2015 to the third quarter of 2022 (in billions of euros), INTAGUS based on Statista 2023, published in October 2022
In addition, shifts in consumer spending occurred, particularly in 2020. The food retail sector, for example, benefited from this, as it was one of the few brick-and-mortar sectors that remained open and provided an alternative to canceled restaurant visits.
Retail sales trends in Germany by sector in 2021 (compared to the previous year). Source: Statista 2023, published in February 2022.
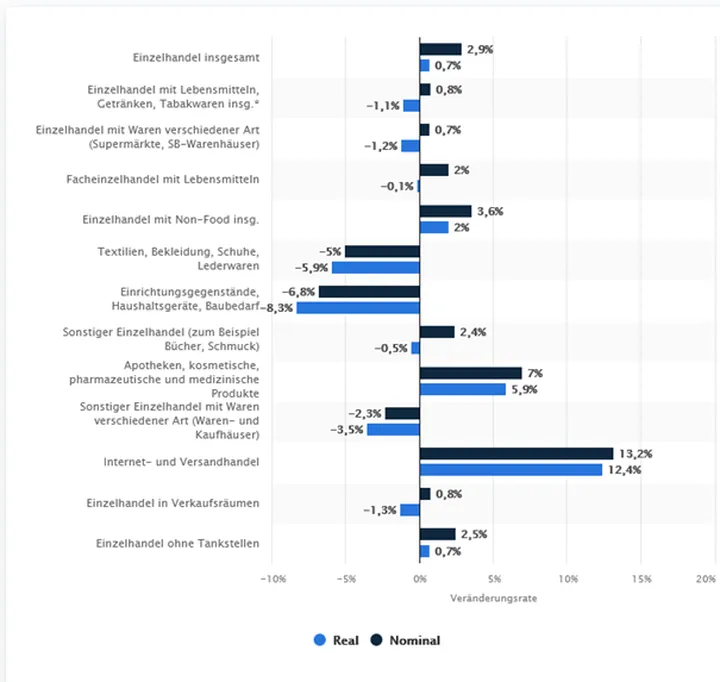 Source: Retail turnover trends in Germany by sector in 2021 (compared with the previous year), INTAGUS, based on Statista 2023, published in February 2022
The impact on purchase prices in this regard is not clear-cut. Buyers feel vindicated in their assessment that companies which suffered under the COVID-19 measures pose a greater risk. In the case of crisis winners, however, it is often argued that these are “merely one-time effects” that cannot be replicated in the future. As a result, even crisis winners often command relatively low multiples because a relatively low purchase price (often based on pre-2020 revenue and earnings) is agreed upon for the relatively high profits of recent years. In brick-and-mortar retail, the COVID-19-related loss of revenue was largely—or at least partially—offset by government support measures, thereby preventing a sharp decline in EBIT multiples.
Retail vs. Wholesale
Even if the sector were simply called “retail,” a distinction would still need to be made between retail and wholesale. Both of these traditional forms of commerce have held a firm place in the postwar economic system. However, in the wake of digitalization, more traditional business models and supply chains are being called into question. This particularly affects the wholesale sector, which faces fierce competition from online retailers and online platforms. The wholesale sector, which is primarily characterized by B2B business, often relied on the business model of its own customers—such as tradespeople, who offered their services at a lower price as part of a mixed-cost calculation because they could offset the difference with the margin from reselling materials and goods purchased from wholesalers. However, when end customers now order a bathtub much more cheaply directly online, the tradesperson loses the opportunity for cross-subsidization, and the wholesaler loses that revenue.
This trend, however, is not new; it has been emerging for nearly 10 years now. The following figures provide an initial assessment of how the retail sector has evolved over time. For example, real wholesale revenue in 2019 was only just under 6% above the 2015 level.
Starting in 2021, the effects of rising inflation become apparent in addition to the negative impact of digitalization on retailers’ revenue. Thus, price-adjusted wholesale revenue remains at the 2021 level, while nominal revenue—that is, the revenue reported on the income statement—fully reflects inflation and rises sharply. In the retail sector, real revenue actually declines, while nominal revenue rises here as well.
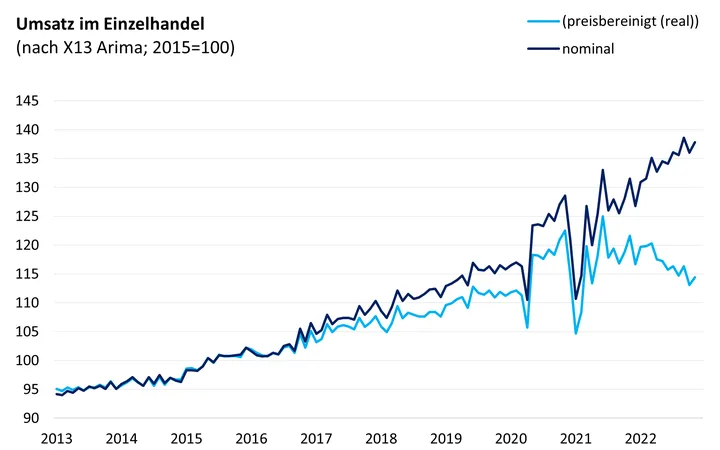 Image1: Retail turnover 2013–2022
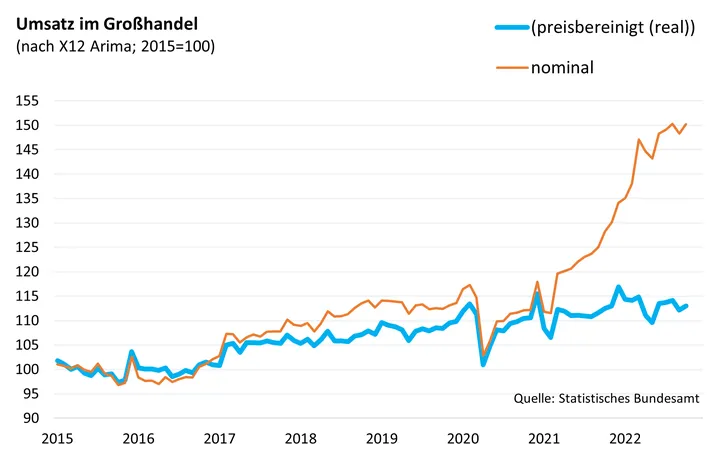 Image 2: Wholesale turnover 2015–2022
High inflation rates pose particular challenges for those valuing retail companies. When preparing planning and forecasting calculations, the first question to answer is what inflation rates should be assumed for the coming years. Based on this, a plausible assumption must be made regarding how the company’s own costs—specifically, wage agreements—will develop, and how purchasing power and, consequently, customer buying behavior will change.
Even though such considerations are often not taken into account—or only briefly addressed—in many multiple-based valuations, the risk situation is nevertheless reflected in more subdued valuations, i.e., lower multiples.
Sector vs. Industry
Another important aspect that should not be overlooked in the context of a valuation is the fact that, strictly speaking, the “retail” sector is not an industry at all, but rather an entire sector. The economic classification into sectors (primary production, manufacturing, trade, services) describes the type of value creation carried out within a company, whereas industries are more closely aligned with the company’s core business; for example, we include not only automakers but also auto dealers in the automotive industry.
As described above, not all industries have been equally affected by the COVID-19 measures. Those industries toward which demand has shifted have been able to benefit from this, and in principle, this applies to both manufacturers and dealers.
When valuing a company using multiples, therefore, not only the multiple of the retail sector but also that of the “actual” industry should be taken into account.
Additional Factors
As an interim conclusion, it can certainly be stated that the breadth of variation in the multiples stems solely from the breadth of this segment’s definition. This variation arises in part from characteristics that have not been of significant importance over the years.
Typical Characteristics of the Group
When using multiples for valuation, the definition of the peer group—that is, the group of companies considered to be as comparable as possible to the company being valued—is of paramount importance. Unlike in valuations where one can access the figures of capital-market-oriented companies, the figures from sales in the SME sector are not publicly available for data protection reasons. To preserve anonymity, the data at DUB.de is therefore “pre-sorted” into established groups, thereby forming standard peer groups on which assessments are based.
A peer group should be as homogeneous as possible in its risk-reward profile. For companies in the e-commerce and retail group, the following characteristics are typical of this group and, in some cases, distinguish it from other groups:
No in-house manufacturing
Largely interchangeable/homogeneous goods
Profit is derived from the purchasing margin
Distribution function
High revenue per employee
Inventory turnover is a key metric
A typical problem for brick-and-mortar retail is inventory management. Large warehouses tie up a lot of capital and cost a lot of money, but in return offer the advantage of better delivery capabilities. In the e-commerce and retail sector, however, inventory management cannot be considered typical, because dropshipping has established itself as a business model among young e-commerce companies. With dropshipping, it is not the retailer itself but another service provider (as is the case, for example, with Fulfillment by Amazon—FBA) or the manufacturer itself that handles delivery to the customer, as well as returns management and similar services.
Dropshipping companies therefore focus their own operations solely on online marketing and sales. From an economic perspective, this is thus less a matter of retail and more a matter of brokerage—that is, a form of service.
Consider the Context of Multiples
It is often overlooked that valuation experts use multiples merely as a method to validate the actual valuation based on future success. This is because, unlike the valuation models used in the income approach or the DCF method, multiples are not purely numerical values, since they are based on prices that were actually negotiated and agreed upon. However, this means that other factors unrelated to value may also have played a role in the negotiations.
Very low multiples arise when sellers—for example, due to poor health—are willing to sell their business at a low purchase price solely to “close the deal.” Since demographic shifts have long since and increasingly transformed the market into a buyer’s market, more and more business owners are realizing that they will no longer be able to command a high purchase price.
Very high multiples arise when companies themselves demonstrate very strong performance and the business owners have no need to sell their shares at a low purchase price. Furthermore, acquirers are often willing to pay a high purchase price if they hope to gain expertise, new technology, new employees, or new customer segments as a result. This frequently applies to companies that are already well-positioned digitally.
Incidentally, while a high return on sales prior to the sale is generally—though not always—a prerequisite for a high purchase price, if the buyer intends to increase a company’s profitability through optimization measures, they will accordingly see less potential for optimization in companies that already have a high return on sales.
Owner Dependency
Whenever succession is involved, owner dependency plays an important role. Many entrepreneurs who have not established a management structure realize too late that they have effectively blocked the sale of their company. They did not realize—or realized too late—that they were trying to sell a company without leadership. But what is a boat worth without a rudder?
This is likely to affect many small, family-run retail businesses. If a sale were to take place at all in such cases, it would typically be at a low multiple.
E-commerce companies are, from the outset, much more digitally oriented. This implies two assumptions: first, because of the digital business model, all essential processes are also digitized—that is, integrated into the company—and are therefore no longer dependent on the entrepreneur. The higher degree of digitization thus also indicates a lower degree of owner dependency. Second, it can be assumed that entrepreneurs in the e-commerce sector are likely to be slightly younger on average, and therefore the majority of the observed transactions are not succession-related purchases, but rather sales that occur primarily because of a favorable offer.
The Customer Generation
In the foreseeable future, members of Generations Y and Z will make up the majority of the customer base. These generations are predominantly digital, with purchases made via smartphone. This fundamental trend generally leads to higher multiples for the e-commerce sector and lower multiples for brick-and-mortar retail.
Conclusion
In conclusion, it can therefore be stated that high multiples are generally achieved by highly profitable companies and those with very positive future prospects. Traditional brick-and-mortar retail companies, on the other hand, tend to change hands at relatively low multiples due to their business model.


