


Private Equity in the Context of Business Succession
Due to demographic change, German small and medium-sized enterprises (SMEs) are facing a major wave of succession. By 2030, about one in three owner-managed companies will be facing a handover. Often, there are no successors within the family. At the same time, interest is growing among professional financial investors, who currently have substantial capital at their disposal and are seeking suitable investment opportunities. However, private equity firms contribute not only capital but also management expertise. To achieve the returns of over 20% demanded by their investors, financial investors typically use three levers for value creation:
Multiple Expansion
Financial engineering
Operational Excellence
As part of multiple expansion, financial investors seek to increase the purchase price multiple over a holding period of approximately 5 years. This can be achieved by selecting an attractive industry or through the inorganic growth of portfolio companies. In the latter case, acquired platforms can grow through add-on investments as part of a “buy-and-build” strategy. Generally, higher purchase price multiples are paid for larger companies.
Financial engineering exploits the so-called “leverage effect,” whereby the return on equity can be “leveraged” through increased use of debt.
In addition to optimizing the capital structure and increasing the purchase price multiple, value creation by financial investors within the framework of operational excellence lies in improving the portfolio company’s operational performance. The goal may be to achieve revenue growth as well as increased profitability—often measured by the EBITDA margin—along with working capital optimization. To develop and implement appropriate measures, financial investors draw not only on their own staff but also on their network of industry experts. Whether on the executive board or serving on a kind of advisory board, these experts act as sparring partners for the (often new) management team following the departure of the previous owner.
The financial investor’s goal is to sell the company to another financial investor or a strategic investor after a holding period of 4–6 years. Alternatively, for larger companies, an initial public offering (IPO) may be considered.
Succession Transactions from the Perspective of Financing Banks
The upcoming succession solutions in the German SME sector represent an attractive business opportunity not only for private equity investors but also for their lenders, including commercial banks. However, these debt-financed acquisitions (so-called “leveraged buyouts,” or LBOs) represent a financing product for the banks that is characterized by increased credit risk, partly due to the value-creation approach of the private equity investors.
As part of an LBO, the private equity fund establishes a special purpose vehicle (SPV), which is capitalized with equity from the fund and debt from the financing partners. This SPV then purchases the shares in the target company and is subsequently merged with it. In this way, the acquisition financing is transferred to the acquired company (known as a “debt push-down”), which is now solely responsible for servicing the debt associated with this financing. From the lenders’ perspective, this is known as “non-recourse financing,” since only the acquired company is liable for the debt; there is no recourse against the private equity fund as the owner. This creates a high credit risk for the bank, which is priced accordingly (“non-investment grade”).
In addition to adequate pricing, however, the credit decision-making process and monitoring during the term of the loan must also be structured in a manner appropriate to the risk.
A Bank’s Lending Process in the Context of an LBO
The borrower’s low creditworthiness in such an LBO leads to very strict requirements for banks’ lending processes. Banks’ creditworthiness assessments in the context of buyouts go beyond an analysis of traditional credit metrics:
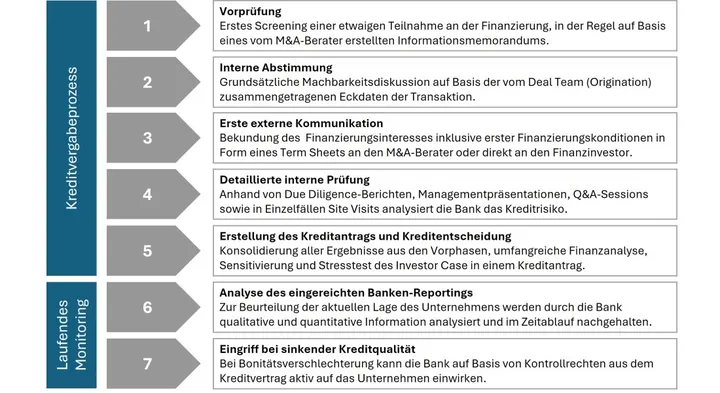 Figure: Idealized Lending Process of an LBO Bank, Prof. Dr. Dirk Dreyer
Since an LBO transaction essentially involves financing the purchase price, the company’s cash-generating capacity—rather than its assets—is of decisive importance for the financing bank’s credit decision. In this “cash flow-based lending” approach, the company’s debt capacity—and thus the bank’s loan offer—is determined by free cash flow (FCF).
In the first step, after analyzing the company’s market attractiveness, competitive position, and USP, the bank assesses the stability of the business model. A positive assessment is the first hurdle the succession transaction must clear to be financeable (“LBO-eligible”). If the business model is not deemed sufficiently stable, the bank approached will decline to provide financing. However, if the preliminary review is successfully completed, the lenders will make an initial decision in principle regarding potential participation and a possible financing structure in internal committees and communicate this to the potential borrower or the inquiring private equity investor. Given the specific nature of the financing transaction, the bank’s preliminary credit decision also takes into account its assessment of the private equity investor and its industry experience, including its expertise in buyout situations. If the financing is to be pursued further, the bank will begin a detailed evaluation of the due diligence reports originally prepared for the financial investor. If no deal-breakers are identified during this step of the process, the deal team will begin preparing a loan application. In this process, the company’s historical performance is first analyzed. As part of the financial modeling process, the business case submitted by the financial investor is subjected to sensitivity analysis and a stress test, and the resulting trends in the relevant financial metrics are reviewed. Based on this, the debt capacity is determined in order to validate or revise the indicative financing structure from the preliminary phase. If the initial financing offer proves acceptable to the client as the transaction process continues, the deal team will submit the loan application to its committees to obtain loan approval. If the relevant decision-makers vote in favor, a loan agreement in accordance with the resolution can be signed and, once all disbursement conditions are met, the loan can be disbursed.
Unlike other acquisition scenarios, the increased credit risk associated with succession planning presents a particular challenge from the bank’s perspective, as the comprehensive and consistent financial data necessary for a well-founded credit decision is often unavailable. While the financial due diligence conducted prior to the transaction can help in this regard, the analytical effort required is nevertheless above average due to the nature of the data available.
Key Challenges for All Parties Involved in Succession Situations
Resulting challenge for the financial investor
While the departing managing partner has built up company-specific knowledge over the years, it is essential for the financial investor—given the relatively short holding period—to quickly gain an overview of the company’s current situation in order to immediately increase profitability as part of value creation. To this end, prior to the acquisition, the investor conducts what is known as “due diligence,” during which external consultants examine the target company from various perspectives. These include commercial, tax, and legal perspectives. The financial situation is analyzed through financial due diligence conducted by certified public accountants.
Once the acquisition is successfully completed, one of the financial investor’s first steps is to introduce or improve the internal reporting system of the new portfolio company. An adequate data foundation for quantifying “Key Performance Indicators” (KPIs), which will guide the company’s future management, is a necessary condition for increasing the company’s value. This transparency, documented in writing, is typically lacking in legacy systems and must be established promptly.
Resulting Challenges for the Financing Bank
The significantly increased debt of the acquired company resulting from an LBO heightens its sensitivity to economic fluctuations. A potential loss of the ability to service debt increases the credit risk for banks and the risk of insolvency for the company itself. To identify this risk early on after the loan is granted, intensive monitoring by the financing bank throughout the term of the loan is essential. Not only during the loan decision-making process but also in the years that follow, the bank faces the challenge of, on the one hand, allowing the borrower sufficient leeway for further development, while on the other hand retaining the ability to intervene promptly should credit-related difficulties arise.
As a result, the loan agreement imposes numerous new obligations on the borrower. In addition to a collateral package, the agreement includes extensive behavioral obligations, representations, and financial covenants—that is, specific financial ratios that must be maintained. Comprehensive quarterly reporting to the bank is also required. In addition to qualitative descriptions of business performance, this typically includes a balance sheet, income statement, and cash flow statement with year-over-year and quarter-over-quarter comparisons. Financial covenants—which, among other things, set the maximum debt level in relation to EBITDA (“leverage covenant”)—are also reviewed on a quarterly basis. Management must confirm the accuracy of the calculated key figures in writing in a so-called “compliance certificate” as part of the reporting. In addition to a reliable historical data set as part of the lending process, regular reporting and valid forecasting of performance metrics such as EBITDA and FCF are therefore of central importance to financing banks during ongoing monitoring.
Resulting Challenges for Companies in Succession Transactions
Both equity and debt investors demand an unprecedented level of financial transparency from the target company. The resulting high demands on the company—particularly on its accounting and controlling functions—pose a significant challenge both during and after the acquisition. Often, the necessary personnel and reporting systems are not available at the time of the transaction. Experience also shows that dealing with a very comprehensive and restrictive loan agreement—with corresponding (disclosure) obligations—repeatedly poses problems for management; therefore, this issue should be given close attention in the run-up to a transaction to ensure the deal is financeable from a bank’s perspective in the context of a succession transaction. During the holding period, the financial investor can and will provide support in this regard.


