

Avalanche Risk? The Succession Problem Could Overwhelm Some Business Owners
Just as after the 2008–09 financial crisis, an increase in acquisitions is expected following the current crisis. This is desirable in order to manage the anticipated high number of business succession cases. In addition, the acquisition of companies emerging from insolvency will gain importance in the future, as an increase in such cases is also anticipated.
The age distribution of business leaders alone suggests that the need for succession planning will soon increase. The database used, for example, by Creditreform lists a total of 1,013,196 manufacturing, retail, and service companies (excluding restaurants and agriculture) with annual revenues between 250,000 and 50 million euros. Among these, 798,572 companies are listed as having 823,170 shareholders with at least a 50 percent stake. The proportion of those over 55—at 374,866—already stands at 45.5%.
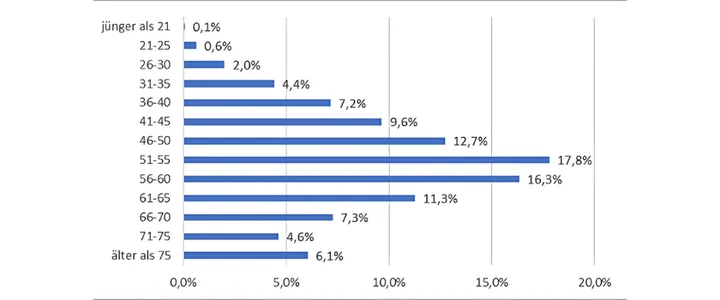
Percentage age distribution of entrepreneurs with at least a 50 percent ownership stake in German small and medium-sized enterprises (SMEs) according to “Markus”
18 percent of majority shareholders are of retirement age, and 30 percent are over 60 years old. If succession planning for this group is to be resolved within the next five years, this will affect an average of 6 percent of companies per year.
That is roughly twice as much as the arithmetic annual average for a generation aged 30 to 35, which stands at around 3 percent. And five years is the preparation time needed to “get the company ready” for a succession process, mitigate risks, and increase its marketability and enterprise value.
In line with the experiences of the 2008–2009 financial crisis, con|cess is seeing today that many entrepreneurs seeking a successor are currently putting their succession efforts on hold, especially if these are to be—or must be—resolved through a sale to a third party.
This is because the financial performance of some industries is suffering from the COVID-19 pandemic, and the outlook remains uncertain. This has a negative impact on both current valuations and the interest of potential buyers.
The understandable approach for many is to wait it out and only re-enter the succession market once business results show a sustained upward trend. Consequently, it is expected that, following the COVID-19 crisis and an equally anticipated realignment of market participants, there will be a significant revival in succession activity.
At the same time, however—and this is the good news for sellers—the number of young entrepreneurs who are able to launch their own businesses by acquiring an existing company is expected to rise noticeably again. This is shown by con|cess’s analysis of the KfW Start-up Monitor for the years following the 2008–2009 financial crisis: From 2008 to 2010, business start-ups resulting from company and equity acquisitions rose by 27 percent; in 2011, the figure was still 21 percent higher than in 2008. However, these figures include all companies, including smaller ones.
The number of companies acquired by new entrepreneurs rose from 48,000 in 2008 to 84,000 two years later and reached as high as 92,000 in 2011. The number of active equity investments increased during the same period from 167,000 to 188,000 and returned to the 2008 level of 167,000 in 2011.
Therefore, entrepreneurs facing succession issues are advised to use this time to better prepare for their future succession. Among other things, a so-called vendor due diligence can be useful for this purpose. Through such an internal review—compiling and updating all documents and information required for a sale—potential areas for risk mitigation and opportunity expansion become apparent, which can be leveraged to optimize the company and its value in the near future.


