

Image: iStock/Nektarstock
Many people dream of starting their own business. Working independently, bringing ideas to life, and taking on responsibility—these are the driving forces behind entrepreneurship. But while most choose to start a new business, taking over an existing company presents an often-overlooked opportunity: the chance to carry on a life’s work while also putting your own stamp on it.
The issue of succession affects not only founders but also those handing over the business. Anyone who has built a business bears responsibility for employees, customers, family, and their own life’s work. That’s why planning for business succession early on is so important. Sudden events such as illness, accidents, disputes, divorces, or unexpected life changes can throw everything into disarray. Added to this is the ongoing shortage of skilled workers, which makes it increasingly difficult to find suitable successors. Well-organized succession planning helps avoid unintended consequences and ensures that the business remains in the right hands.
In Germany in particular, an entire generation of entrepreneurs will face the question in the coming years: Who will carry on what has been built up over decades? Countless businesses are looking for successors, often without having planned ahead in time. For potential successors, this opens up one of the most exciting phases in the life of a small or medium-sized business, with enormous potential—provided they are ready to take on the responsibility.
Two Paths, One Goal
Starting a business from scratch offers maximum freedom: your own business model, your own brand, your own culture. But it also requires courage, capital, time, and a great deal of perseverance. A market must first be tapped, a team built, and processes established—and it often takes years before success materializes.
With a business succession, on the other hand, you’re not entering uncharted territory. Structures, customer relationships, and employees are already in place. That doesn’t mean everything stays the same, but the foundation is laid. Whoever takes over steps directly into a functioning business and can shape its future from day one. These initial advantages make succession a more realistic and economically stable option for many founders.
The Underestimated Opportunity of Business Succession
Many succession plans fail not because of a lack of interested parties, but because of a lack of preparation. A succession plan requires time for valuation, discussions, and tax and legal structuring. Those who start too late lose their ability to shape the process. Yet early planning can bring enormous benefits: tax relief, clear structures for heirs or buyers, and the assurance that the business will end up in good hands.
Emotions play a particularly significant role in intra-family transfers. It’s not just about numbers, but about trust, responsibility, and continuity. A successful succession is achieved when economic rationality and human factors are given equal consideration. This requires tact and experience in guiding such processes.
Challenges That Are Worth the Effort
Of course, a takeover isn’t a sure thing either. Anyone who takes over a company also takes on its history, with all its opportunities and potential legacy issues. It’s important to review structures, involve employees, and carefully introduce one’s own ideas. But that’s precisely what makes it so appealing: preserving what already exists while shaping something new.
Financially, a takeover may initially seem more demanding because a purchase price must be covered. But in return, you avoid much of what founders have to painstakingly build from scratch, such as brand awareness, reputation, customers, and well-established processes. Often, a business can be put on a growth trajectory in a short time with manageable adjustments.
Plan Ahead and Seek Professional Guidance
A successful succession is no accident—it’s the result of careful planning. The tax and legal issues involved are complex. Should the business be sold, given away, or passed down as an inheritance? What’s the best way to transfer business assets from a tax perspective? What is the right legal structure? And what happens in an emergency when immediate action is required?
Clarifying these questions early on provides the confidence to act. Succession planning should begin several years—at least three to five years—in advance. It requires expertise, strategic thinking, and an understanding of the individual goals of all parties involved.
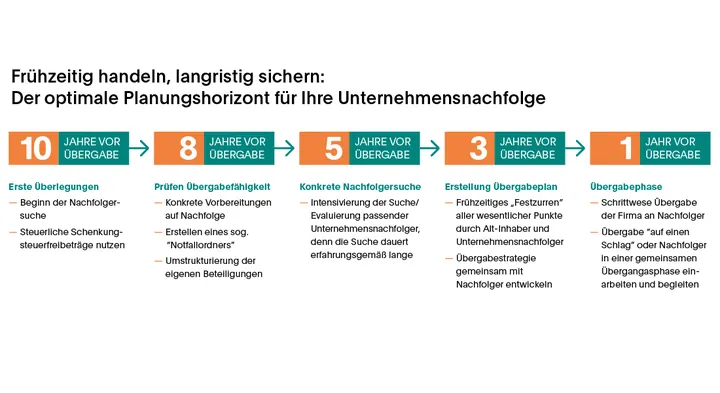
Image: ETL
Experience Makes the Difference
Precisely because succession planning is so multifaceted, it requires advisors who can think outside the box. Tax, legal, and business aspects are intertwined and must be woven into a tailored, comprehensive plan.
The experts at the ETL Group have been supporting small and medium-sized businesses with precisely these issues for many years. Their approach: not just organizing numbers, but creating new perspectives. With a network of tax advisors, attorneys, and management consultants, ETL supports entrepreneurs in securing their life’s work or successfully continuing an existing business: with foresight, structure, and an understanding of the human side of business decisions.
Shaping the future means acting in a timely manner
Whether starting a business or taking over a family business: both paths lead to self-employment. But while starting a business is often seen as a bold move, taking over a family business is an equally bold step—one that involves taking on responsibility and building on what already exists.
Those who address their entrepreneurial future early on can take advantage of tax benefits, minimize risks, and strategically shape opportunities. A well-thought-out succession strategy isn’t just a formality—it’s an investment in stability, value, and future viability. And that’s precisely where the underestimated potential lies: whoever takes over isn’t starting from scratch, but building on the foundation of a well-established vision.


