

A business valuation may be necessary for a wide variety of reasons. Possible reasons include, for example, taking out a loan, raising capital, or even a sale as part of a business succession plan. This leads to very different areas of focus within the context of a business valuation.
But this is where the areas of tension begin. Naturally, as long as the seller is an individual—such as the founder—they tend to focus on the past and have a subjective impression of their company’s value. Overtime, weekends, even occasional hard times, and the risks taken clearly demonstrate to them that building this company to its current state required a great deal of effort and hard work. This should now be reflected in the sale price.
A potential buyer, however, takes the exact opposite perspective: they have little interest in the past. Instead, they want to shape the future with the company and, for this very reason, expect a future return on their investment.
“A large fortune is no guarantee of a good return.”
Equally contrasting are the views on existing assets and potential returns. In extreme cases, it may be appropriate to value a company solely based on its existing corporate assets (net worth). Here, fixed assets and any financial assets play the key role.
However, the assessment of a company’s earnings performance is entirely independent of its assets. A large asset base is no guarantee of a good return. Conversely, however, a high return can be generated even with limited assets. Capital-intensive industries such as mechanical engineering will therefore exhibit different key figures here than, for example, service providers. Consequently, in extreme cases, the focus on profitability can represent a valuation perspective all its own.
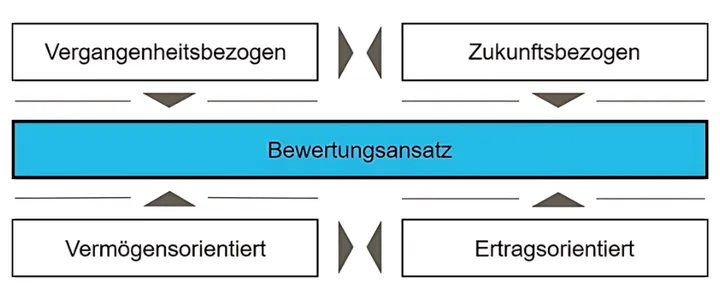
Fig. 1: Tension Between Valuation Approaches
As a rule, this tension between approaches will not manifest in extreme positions during a business valuation. Instead, multiple perspectives must always be considered—and thus factors that do justice to all sides. However, it becomes clear that every business valuation can have focal points and perspectives that have a decisive influence on the result. The various valuation methods each reflect these differences.
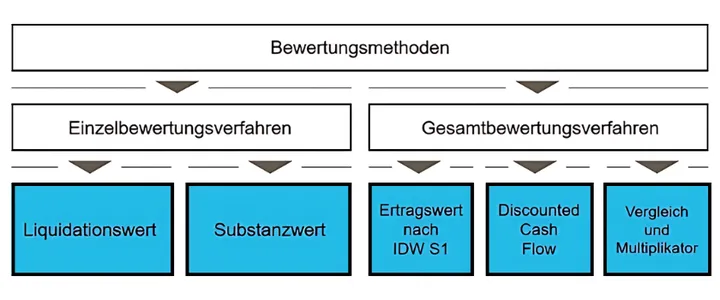
Fig. 2: Valuation Methods
Individual Valuation Methods Based on Tangible Assets
The group of individual valuation methods includes the liquidation value and the net asset value. The liquidation value is based on the assumption that the company is liquidated immediately. The company’s assets are therefore valued individually at their break-up or liquidation values, totaled, and liabilities deducted.
In contrast to the liquidation value, the net asset value method values the assets at replacement costs. It is thus based on the question of what it would cost to rebuild and continue the company in its current form.
Both individual valuation methods are thus based primarily on assets and do not take into account, for example, market position, customer relationships, or future opportunities.
Income-Based Valuation Methods
In contrast, the income-based valuation methods are not based on assets but on the amount of past or future net income. The primary focus is on how quickly the purchase price of the company can be recouped through profits.
The income approach according to IDW S1 is the most widely used method in Germany; it has been established by the Institute of Public Auditors in Germany (IDW) as the standard for public auditors and tax advisors and is recognized by the tax authorities.
The operating results for the last three years, as well as the projected figures for the current and the next two years, are adjusted for extraordinary and one-time expenses and income—such as special depreciation and insurance compensation—for the purpose of the valuation. To ensure comparability in the valuation, key individual items—such as managing director salaries—are also standardized using a cost-based approach.
The company’s future earning power is ultimately determined based on the adjusted figures and the projected figures. This earning power serves as the basis for a company value in the subsequent capitalization process, taking into account an interest rate for an alternative investment in the capital market and an industry- and company-specific risk premium.
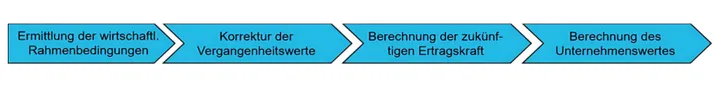
Fig. 3. Procedure for Using the Income Approach
The discounted cash flow(DCF) method is fundamentally very similar to the income approach. However, it uses future cash flow as its basis, making it a purely forward-looking method that is typically used for larger companies. The method is internationally recognized and therefore frequently serves as the basis for valuation in international corporate sales.
The major advantage of the high degree of formalization in both the income approach and the DCF method is also its greatest disadvantage: Both methods take the current market situation into account only through risk premiums. However, the market value of the company plays a major role, particularly in the context of a corporate sale or acquisition. For this reason, the multiplier method is frequently used in such cases, as it allows both EBIT and revenue to be used as indicators of a company’s value.
The adjustment of actual and projected figures is performed in the same manner as in the income approach or the DCF method. Subsequently, a weighted average is calculated from the adjusted actual and projected figures. Finally, to calculate the enterprise value, appropriate multipliers—which serve as factors for the weighted average—are applied depending on the industry and the size of the company. These multipliers are regularly derived from completed transactions involving comparable companies and are published. Calculating a company’s value using the multiplier method is thus similar to a real estate appraisal (value = x times annual revenue).


