

At the same time, the number of corporate transactions in the SME sector is growing, and with it the need for valuations that appropriately take into account the specific characteristics of SMEs. As part of a meta-analysis, we have examined the current state of research and practice in SME-related business valuation and provide a brief overview in this editorial.
Introduction
Small and medium-sized enterprises (SMEs) constitute the largest economic sector in every economy—whether in industrialized or developing countries—and thus play a significant role worldwide.1 According to the European Commission’s definition,99.5% of all companies in Germany are classic “small and medium-sized enterprises (SMEs).”2
They are generally highly diverse in terms of size, age, industry, ownership, and business model. Furthermore, market-based comparative data is usually not available to the appraiser. Due to these unique characteristics, the valuation of SMEs is a complex process that differs in various respects from the valuation of large publicly traded companies.3
Business valuation is, overall, a much-discussed topic. In practice, theory, and case law, various approaches, guidelines, and standards are presented to conduct an appropriate valuation on a case-by-case basis.4 These are generally not tied to the size of a company. However, their underlying assumptions are predominantly shaped by the valuation of large, capital-market-oriented companies.5 A satisfactory and uniform methodfor valuing SMEs is therefore still being sought.6 For reasons such as succession planning, the number of corporate transactions involving SMEs has risen in recent years.7 This upward trend is expected to continuein the coming years.8 As partof a meta-analysis, we have examined the state of the art in both academic research and professional practice regarding SME-related business valuation and provide a brief overview in this editorial
Objective of the Analysis
This editorial initially summarizes only the key findings of the analysis conducted between January and May 2022. Since there is a wealth of literature on the topic of SME-related business valuation, selected articles were examined using a meta-analysis, and the results are presented in a highly condensed form. To this end, we first examined the fundamentals of SMEs and business valuation in general. The meta-analysis was then conducted, focusing on the valuation methods relevant to SME valuation and the specific considerations that must be taken into account. We plan to address individual aspects in greater detail in future articles. Finally, the study also addressed the impact of digitalization on business valuation and on the methods presented in this research, as digital changes—both today and in the future—will affect business valuation in various ways. The meta-analysis was conducted as part of a master’s thesis in cooperation with the University of Paderborn.
Basics of the Analysis
During the initial stages of collecting and categorizing the academic literature, it became apparent that the individual articles differ significantly in terms of their specific topics and can only be superficially classified under the broader topic of SME valuation. A total of approximately 50 sources and articles were included. Some authors describe the specific characteristics of SMEs in general or in the context of currently relevant valuation methods. Others focus on selected valuation methods, valuation parameters, and their application to SMEs. Still others deal solely with individual components, such as the appropriateness of adjustments—either upward or downward—to account for SME-specific characteristics.9 It shouldalso be noted that the existing literature, particularly in German-speaking countries, is extremely practice-oriented, and in-depth theoretical analyses are found only sporadically.10 A direct comparison of all articles in the sense of a meta-analysis is therefore rather difficult, as such a comparison requires high-quality, quantitative, and, above all, uniform studies.11 Taking this issueinto account, the meta-analysis was conducted in such a way that the individual contents of the scholarly articles could be compared as effectively as possible and subsequently summarized and organized by topic.
The search for scholarly literature on the topic of SME valuation yielded results primarily from German- and English-speaking countries, though there were also a few articles from Asia and South America. An initial analysis of the collected scholarly literature revealed that valuation practices differ among individual countries. U.S. valuation practice, for example, relies on more or less precisely selected discounts for valuing SMEs.12 In German-language theory, however, this approach is controversial.13 Due to the significant international differences and the goal of providing a clear overview of SME valuation, the analysis focused almost exclusively on German-language scholarly articles. The legal foundations already outlined also focused solely on Germany, so the theory of SME valuation now follows accordingly. Comparisons with approaches in other countries were mentioned in some places solely for illustrative purposes.
Through the analysis of the selected scholarly articles, a wealth of information was obtained regarding the application of valuation methods to SMEs as well as the characteristics that must be taken into account. The authors rule out valuing SMEs exactly as large corporations are valued, since there are specific characteristics typical of SMEs that must be considered.14
Key Findings of the Analysis
Even the definition of SMEs is not clearly established, meaning there is no uniform designation at either the international or national level. In German-speaking countries, the definition is often based on the European Commission’s 2003 definition. According to this definition, a company is classified as an SME if it has no more than 249 employees and generates an annual revenue of no more than €50 million or has a balance sheet total of no more than €43 million.15
Nor are there any fundamental guidelines from the German legislature regarding business valuation. It is only legally prescribed in principle for valuation purposes related to inheritance, income, and gift taxes, or in the context of the right to a compulsory share. Examples worth highlighting here include the simplified income approach and, in particular, the modified income approach. The latter is based on a separate, standard-like guideline set forth in BVS Position 11-2017.16 For all other (legal) purposes, the decision-making authority thus rests with the appraisers and, where applicable, with the courts. These generally rely on professional standards and guidelines such as IDW S 1 or the modified income approach.
The literature agrees that certain specific characteristics of SMEs must be taken into account compared to large corporations. Based on the meta-analysis conducted, it was demonstrated that a majority of the authors in the selected professional literature identify specific characteristics in SMEs, such as a high degree of personal involvement, a lack of fungibility and comparable companies, as well as insufficient data and increased risks. However, how to address these issues methodologically in detail is often not specified with sufficient detail or consistency. Rather, there are differing professional views and approaches among appraisers.
Opinions, however, remain divided on how to account for these specific characteristics in the valuation process. Numerous methods are available for valuing a company. Although these methods were originally designed for publicly traded companies, they can in principle also be applied to SME valuations. This applies in particular to the IDW S1 standard as amended in 2008.
In the professional literature examined, authors take varying stances on these methods. The following table provides an overview of the valuation methods mentioned in most articles and illustrates how frequently they are classified as suitable or unsuitable for application to SMEs. Some authors merely explain the procedure of individual methods (neutral), while others offer direct criticism (negative response) or highlight strengths (positive response). It should be noted that the classification of the qualitative articles was carried out to the best of our ability based on subjective criteria.
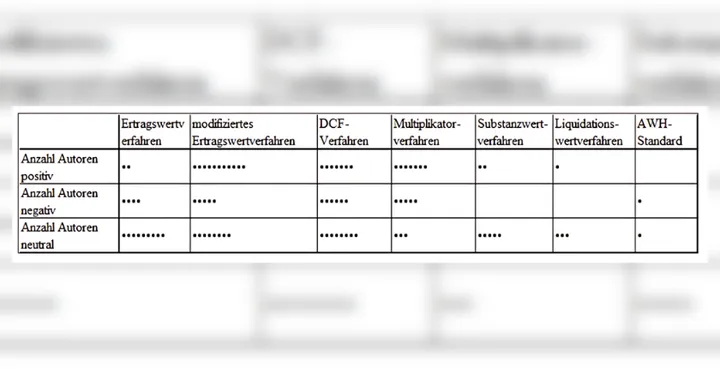
Table 1: Number of academic articles broken down by the author’s stance on specific valuation methods for SMEs (Source: Steinrücken (2022))
Table 1 illustrates the popularity among authors of capital value-oriented methods—particularly the modified income approach—for SME valuation. Other methods are also mentioned in both positive and negative or neutral terms. There is no clear consensus regarding any specific method.
The majority of authors favor the capital value-oriented modified income approach for valuing SMEs, which differs primarily from the classic income approach according to IDW S1 in that it uses a shorter income period. Both in theory and in IDW Practice Note 1/2014, it is recommended that, when valuing SMEs, the influence of the previous owner be assumed and, consequently, a shorter profit period be adopted within which the planned profits are discounted. The adjustment of this period—which reflects the time it would take for an entrepreneur with similar qualifications and comparable business skills to replicate the subject of the valuation—leads, among other things, to the term “modified income approach.” However, the IDW does not provide specific recommendations for determining this period, meaning that subjective assessments by the respective appraiser can lead to varying results.17 Only the BVS, in its published position paper on the valuation of SMEs, specifies future earnings periods of up to 10 years for owner-managed SMEs.
It should be noted that further clarification is needed regarding this method, as there is not yet a completely uniform understanding among the bodies entrusted with business valuations. To date, the BVS Position Paper 11-2017—or its amended version, 10-2022—has provided the most significant basis in this regard.
Criticism of net present value-oriented methods—including the DCF method—is directed in particular at the Capital Asset Pricing Model (CAPM) for determining the discount rate, as its theoretical premises limit its applicability to calculating the cost of capital for SMEs. However, the authors rejected other approaches, such as the total beta method, even more strongly, leaving the CAPM as the best solution. It is argued that, despite its weaknesses, the CAPM is the most convincing method to date for deriving risk-equivalent costs of capital and serves as a sensible starting point for valuing SMEs. However, it is necessary to examine which model assumptions are not met and which SME-specific characteristics should be analyzed in greater detail.18
For the valuation of freelance practices, on the other hand, market-price-oriented methods are emphasized in addition to the modified income approach, since these practices typically exhibit an extremely high dependence on individual key personnel and corresponding ranges of multiples are available in these industries. Individual valuation methods such as the net asset value and liquidation value methods are given less attention by the authors. They are used only in specific cases, such as when a company is being dissolved. Asset-based methods do not hold independent significance.
According to the results of the meta-analysis, several specific considerations must be taken into account when valuing SMEs using net present value-based methods. For example, when projecting future surpluses, an imputed owner’s compensation should generally be applied, which reflects market-based remuneration for entrepreneurial activities. The imputed owner’s compensation should be set at the level of compensation paid to an outside manager and determined regardless of the company’s legal form.19
Tax considerations must also be taken into account, and particular attention should be paid to determining an appropriate tax rate at the owner level when valuing an SME.
An important component of net present value-based valuation methods is the capitalization rate, which consists of a risk-free interest rate and a risk premium. The base rate is determined based on long-term returns on government bonds and adjusted for the maturity of the cash flow; for SMEs, it is generally determined in the same manner as for large corporations. The situation is different for the risk premium—more specifically, for the beta factor it contains. The professional literature reviewed criticizes the fact that no capital market data is available for SMEs and that, as a rule, there are no publicly traded companies from which a beta factor can be derived. As already mentioned, however, there is currently no better solution, so some authors recommend the use of so-called industry betas. There is disagreement regarding the inclusion of additional risk premiums to account for the specific characteristics of SMEs in the valuation. The IDW considers flat-rate discounts in an objective valuation to be inappropriate. Other authors see a need for action in cases of lack of fungibility, heavy reliance on key individuals, or an increased probability of insolvency. This can take the form of discounts when forecasting future earnings (“discounting”) or a premium on the capitalization rate. Even in market-price-oriented methods, specific characteristics can be taken into account through discounts applied to the multiplier. The authors reject a flat-rate size premium, as each company and its risk profile should be considered separately. A detailed and separate analysis of the risk profile of the individual valuation subject is emphasized as essential for conducting a proper valuation.
Ultimately, it must be emphasized that, prior to an SME valuation, both the subject of the valuation and the reason and purpose of the valuation must be clearly defined. Next, a valuation method appropriate for the purpose must be selected. The specific characteristics of SMEs must be taken into account in every case. However, before applying additional risk premiums, the purpose of the valuation should be reconsidered in order to examine, in particular, the admissibility of these modifications on a case-by-case basis.
Digitalization poses further challenges for business valuation. Entire business models and industries may be continuously affected by digital changes, and thus the valuation subjects as well. In particular, their asset structure may change due to an increase in intangible assets, which are subject to certain valuation uncertainties. Due to these circumstances, historical data does not provide a reliable basis, making it more difficult to forecast future earnings. The simulation of various future scenarios is becoming increasingly important.
In net present value-based valuation methods, the derivation of the market risk premium and the beta factor is also affected by this problem. For market-value-oriented companies, the search for comparable companies may become more complex due to changing business models. On the other hand, the use of new, automated valuation systems may, under certain circumstances, offer new opportunities for identifying comparable companies. New tools for the valuation process itself may also simplify it under certain circumstances.
Conclusion
Overall, both in theory and in practice, the picture regarding the valuation of small and medium-sized enterprises remains heterogeneous.
In practice, the valuation of SMEs in Germany receives more attention than it does in theory or the literature. There are numerous viewpoints, recommendations, and scholarly articles on the subject. However, there is a lack of a fundamental definition and framework, which can leave the valuer uncertain due to the differing viewpoints. This is also partly reflected in well-known court rulings regarding the application of valuation methods in SME valuation. There remains a need for further clarification regarding the precise distinction and unambiguous classification of the methods and their specific characteristics. In particular, the term “modified income approach” is still sometimes described and used in different ways, even though the current BVS Position Paper 10-2022 provides a relatively standardized procedure.
Particularly in light of digitalization and the resulting rapid changes—but above all due to the importance of SMEs in the business landscape—it would be desirable for the academic community to engage even more deeply with SME valuation and to formulate clear guidelines and definitions for future valuations. In doing so, there is no need to reinvent the wheel; rather, the approach should build upon standards that have already been established in the market across professional disciplines. Of particular note here are the modifications to the income approach in accordance with IDW S1 as amended in 2008 and IDW Practice Note 1/2014, which are described in detail, for example, within the framework of the Modified Income Approach outlined in BVS Position 10-2022 for SMEs.20
Footnotes
1 See Bayraktar/Algan (2019), p. 56; Arnold (2019)
2 See EU Recommendation 2003/361.
3 See Ihlau et al. (2019), p. 1.
4 See Zwirner (2013), p. 1797.
5 See Schütte-Biastoch (2011), p. 2
6 See Nestler (2012), p. 1271.
7 See Zieger/Schütte-Biastoch (2008), p. 590
8 See Fels et al. (2021), p. 9.
9 See Hackspiel (2010) or Nestler (2012) for general information on SME valuation; Hüttche/Schmid (2019) and Wagner/Ziegler (2021) for valuation haircuts applied to SMEs.
10 This is particularly evident in the practice-oriented professional journals where most of the relevant articles can be found (e.g., *Der Betrieb*, *Betriebs-Berater*, *Der Sachverständige*).
11 See Eisend (2020), p. 6ff
12 See Jonas (2011), p. 305; with reference to Pratt (2009).
13 See Wagner/Ziegler (2021), p. 393; see also Jentsch (2019), p. 230.
14 See Gleißner/Ihlau (2012), p. 312; see also, for example, Hackspiel (2010), p. 131; Zieger/Schütte-Biastoch (2008), p. 590; Wagner/Ziegler (2021), p. 393.
15 See EU Recommendation 2003/36.
16 See Federal Association of Publicly Appointed and Sworn Experts (BVS): Position Paper 11-2017 Valuation of Small and Medium-Sized Enterprises (SMEs).
17 See Butz/Aufenanger (2018), p. 304; see also IDW S1 (2014), para. 23.
18 See Zieger/Schütte-Biastoch (2008), p. 595; for more details, see Drukarczyk/Schüler (2016), p. 245.
19 See Schlimpert: “The Entrepreneur’s Salary as a Value Driver in SME Valuation,” DS 1-2/2019.
20 See Federal Association of Publicly Appointed and Sworn Experts (BVS): Position Paper 10-2022, Valuation of Small and Medium-Sized Enterprises (SMEs).


