


A Critical Approach to ESG Ratings Is Warranted
When comparing ESG ratings between small-cap and large-cap stocks within the European equity market, it is striking that small-cap stocks are valued at a discount over time (Fig. 1).
Fig. 1: Comparison—European small-cap vs. large-cap stocks* Gross excess return: Small-cap stocks outperform large-cap stocks (indexed)
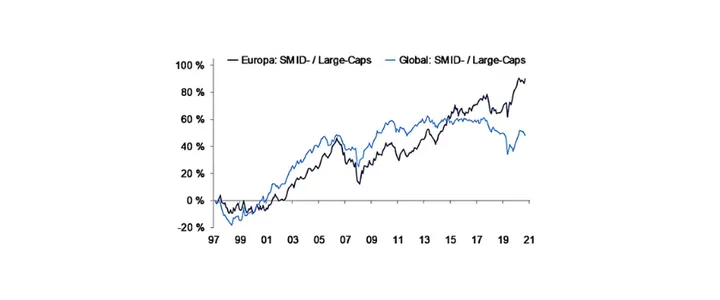
Based on ESG ratings that use weighted averages to facilitate a cross-sector comparison, this discount averaged 5%. When industry-specific ESG ratings are used, the discount increased to 15%.
Since the majority of investors focus on industry-specific comparisons, small-cap stocks face a significant structural disadvantage relative to large-cap stocks. The more simplistically investors differentiate between all-cap products based on ESG ratings, the greater their preference for large-cap stocks over small-cap stocks—a misjudgment, in our view.
This is because smaller companies often cannot draw on the same resources as blue-chip stocks to present sustainability reporting in a similarly comprehensive and detailed manner. This does not mean that small-cap stocks are less sustainable than blue-chip stocks. On the contrary: investors are called upon to take a closer look.
Aligning with ESG ratings is worthwhile to a limited extent
If one differentiates within the European small-cap sector based on industry-specific ESG ratings, a retrospective analysis shows that this was worthwhile (Fig. 2). However, this differentiation had virtually no impact.
Fig. 2: Preference for ESG ratings yielded little return—gross excess return relative to the MSCI Europe SMID, indexed
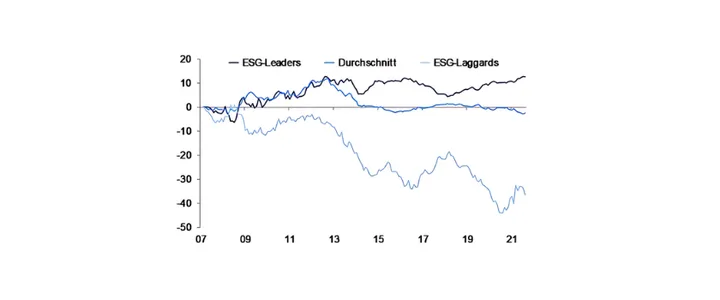
Note: ESG leaders (AAA-, AA- ratings), ESG laggards (B-, CCC- ratings), average (A-, BBB-, BB- ratings). Sources: MSCI, Refinitiv, Metzler
A portfolio of stocks with exemplary sustainability ratings has outperformed the market index by only one percentage point per year since 2007—a meager result. And although a portfolio of laggards underperformed the market index significantly over the same period, this played a minor role in the overall context. This is because these securities accounted for only a small portion of the market capitalization—at the current edge of the index universe, this figure stood at 3%.
A more refined approach, based on the industry-specific ESG score itself, yielded a slightly higher return—but even since 2011, this was true only for the companies to be avoided (Fig. 3). A preference for stocks that either had a high ESG score or showed a positive change in that ESG score (also known as ESG momentum) did not yield any significant excess return relative to the market index over the past ten years. So what really helps to strengthen the risk-return profiles of small-cap portfolios?
Fig. 3: What effect would a preference for ESG scores or for significant changes in these ESG scores have had? Gross excess return vs. MSCI Europe SMID, indexed

Calculation: Based on the scores, securities within the MSCI Europe SMID Cap Index are divided into two halves. These encompass 50% of all securities with the highest (H1) and lowest (H2) scores, respectively. The portfolios are rebalanced on a monthly basis. Gross returns in euros are calculated using market capitalization weights. Sources: MSCI, Refinitiv, Metzler
Avoid stocks that attract negative attention due to controversies
In our experience, owner-managed companies in the small-cap segment pay closer attention to their reputation than companies in the large-cap segment. Furthermore, the less complex value chains of smaller companies are also less susceptible to controversies. In addition, critical NGOs and journalists pay less attention to smaller companies.
It is also worth noting that even after controversies came to light, it was advisable to avoid such stocks. And the more serious the controversy, the greater the negative impact on a portfolio. The risk-return profile of small-cap portfolios could be strengthened by avoiding stocks that were the subject of controversies (Fig. 4). But which stocks are excluded from portfolios in this way?
Fig. 4: The negative impact on the portfolio due to controversies stems largely from cyclical sectors; gross excess return relative to the MSCI Europe SMID Index

Note: Stocks associated with the most severe controversies are marked with a red flag (affecting, on average, about 1% of the market capitalization of the MSCI Europe SMID Cap Index since 2012), serious controversies with an orange flag (5%), and minor controversies with a yellow flag (15%). There have been no red flags within the index since 2018. Sources: MSCI, Refinitiv, Metzler
An analysis of the corresponding risk premium profiles shows (Fig. 5): Stocks with particularly weak growth that exhibit a lower level of quality compared to the small-cap segment—whether in the form of a weak balance sheet, low profitability, or highly volatile earnings profiles—are avoided. Furthermore, sustainable investors do not view the combination of an above-average dividend yield and low valuation multiples as “attractive,” but rather as a risk to be avoided.
Fig. 5: Stocks affected by controversies exhibited a very specific risk premium profile relative to the market: Standardized Z-scores [+/-1] relative to the MSCI Europe SMID Index
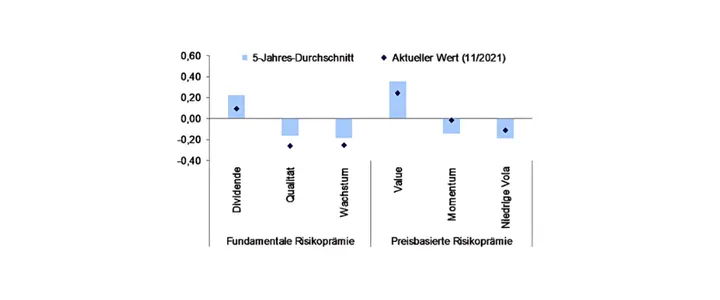
Note: Risk premiums were calculated in accordance with MSCI standards. Z-scores indicate the number of standard deviations a value is from the mean. Exposure is calculated based on market capitalization weights. Values greater than 0.20 or less than -0.20 are considered significant. Sources: MSCI, Refinitiv, Metzler
Investing in Stocks with Positive Impact Exposure
The risks of a small-cap equity portfolio can thus be reduced by avoiding stocks of companies with weak ESG ratings and controversies. The return potential, in turn, can be enhanced by investing in stocks that deliver added value for the environment and society (Fig. 6).
Fig. 6: Impact exposure pays off in the small-cap segment—gross excess return relative to the MSCI Europe Large index
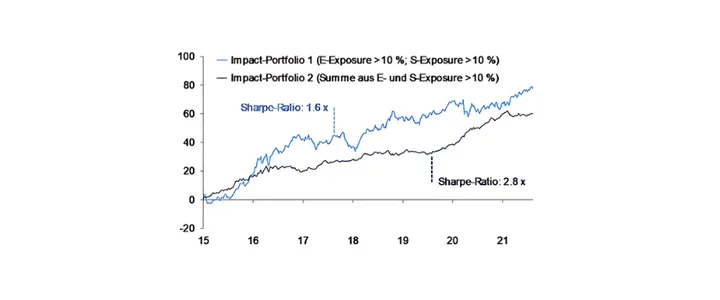
Note: Impact exposure refers to revenues that can be attributed to the UN’s sustainability goals—environmental impact or E-exposure (SDGs: 7, 12–15); social impact or S-exposure (SDGs: 1–6, 8–11). Portfolio 2 consists of 293
Taking the volatility of excess returns into account, a portfolio of securities that demonstrated significant impact exposure—regardless of contributions from environmental and social categories—was preferable. Environmental impact exposure had a stabilizing effect here. The excess returns of securities with high social impact exposure were comparatively lower and were accompanied by higher volatility. But what suggests that a focus on securities with high environmental impact exposure will continue to contribute to excess returns in the future?
First and foremost, the lower Scope 1–3 carbon footprint compared to the overall small-cap market could contribute to this—that is, particularly when taking into account the effects of products and services in upstream and downstream parts of the value chain. This is because, when this footprint is converted into global warming potential using climate models based on estimates from the UN Intergovernmental Panel on Climate Change (IPCC), it can be shown that the portfolio’s global warming potential (2.7 °C) is significantly lower than that of the market (3.3 °C).
The more investment products are aligned with the goals of the Paris Agreement (1.5 °C), the higher the demand for securities with low warming potentials. Looking back, it is already evident that the more pronounced the environmental impact exposure and the lower the warming potential of the companies, the higher the excess return of a portfolio relative to the market (Fig. 7).
Fig. 7: High environmental impact exposure is associated with small- and mid-cap stocks with low warming potential. Observation within the MSCI Europe SMID Index (N = securities
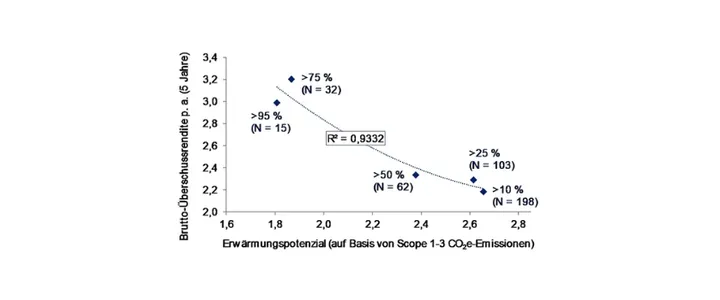
Sources: MSCI, FactSet, Metzler
If this correlation persists, it can be assumed that the impact exposure factor—particularly the contribution from environmental impact—should continue to help stabilize the excess return of such a portfolio in the future. However, in light of the European Commission’s planned social taxonomy, the contribution from social impact exposure should not be underestimated in the future either.
Conclusion: Sustainability as a Performance Lever
Investors seeking to strengthen the risk-return profiles of portfolios in the European equity market by capturing the size risk premium should consistently focus on sustainability.
Four aspects are important here:
A critical review of ESG data is essential to adequately assess the associated opportunities and risks. Only in this way can critical issues be clarified with management to generate added value for portfolio companies.
Differentiating based on ESG criteria has proven to be of little value—neither based on absolute ESG scores (on which the ratings are based) nor on ESG momentum.
We observe that avoiding securities that repeatedly attract negative attention due to controversies reduces a portfolio’s risk exposure.
Return opportunities arise particularly with securities that have high impact exposure—in addition to environmental impact, greater attention will need to be paid to social impact in the future.


