

What applies to publicly traded companies must also apply to the SME sector
Standardized governance ratings are generally available only for publicly traded companies across the board. However, the insights gained from securities markets can also be applied to unlisted companies.
Governance assessments, as part of the ESG or sustainability profiles of publicly traded companies, show a strong inverse correlation with risk metrics. This means that when companies are rated as exemplary in terms of sustainability, this is accompanied by a low risk profile, which in turn is demonstrably reflected in more attractive refinancing terms from their lenders. This relationship should be applicable to banks’ lending practices in the SME sector.
Investors in capital markets reward exemplary governance profiles
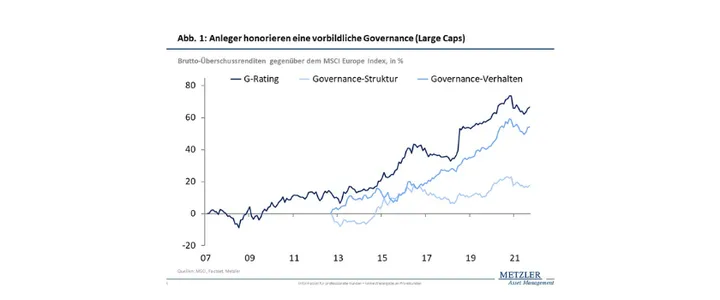
Using European stocks as an example, it can be shown that differentiation based on governance factors has sustainably strengthened the risk-return profiles of portfolios (Fig. 1). However, investors took a more critical view of governance behavior than of governance structure.1 This is because, when stocks that stood out negatively due to misconduct were avoided, greater added value for the portfolio could be achieved in retrospect than when differentiation was based on governance structure.
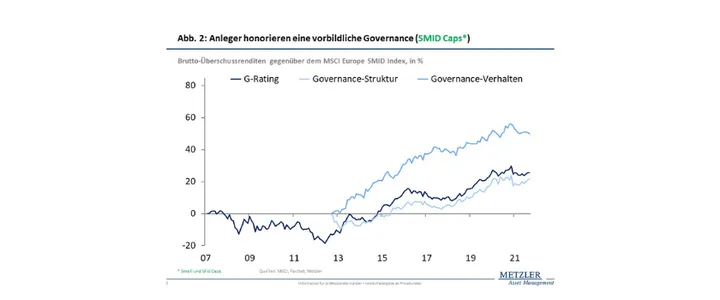
The smaller a company’s market capitalization, the more pronounced this effect was (Fig. 2). There is a specific reason for this: A risk-minimizing governance structure evolves over the course of a company’s development phases and does not necessarily follow a linear valuation pattern. This is because the larger and more complex a company becomes, the more important a strong governance structure is for managing risks arising from value chains and regulations. The assessment of governance behavior, on the other hand, is clear: misconduct is always viewed negatively.
Companies that attract attention due to controversies pay a premium when refinancing
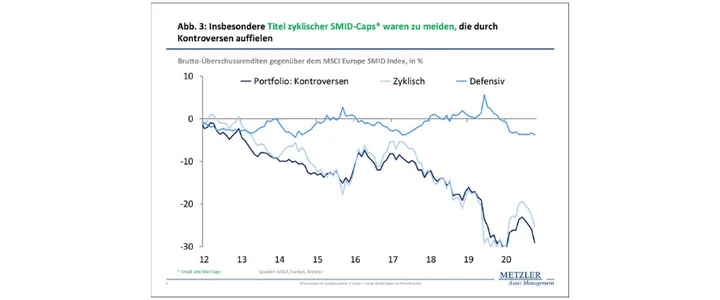
An analysis of the European small- and mid-cap segment of the stock market shows that it has paid off to avoid companies that have repeatedly attracted negative attention due to controversial practices (Fig. 3). It was also worthwhile to stick to this strategy even after the controversy had already become public. The resulting reduction in enterprise value per share implicitly increases the cost of capital when refinancing is to be achieved through capital increases via the stock market. 3
Activist short sellers typically target stocks with poor governance practices
This is particularly evident for small- and mid-cap companies: Violations of laws and deviations from recognized governance principles not only erode corporate value but also increase the likelihood of becoming a target of activist short-selling campaigns. 4
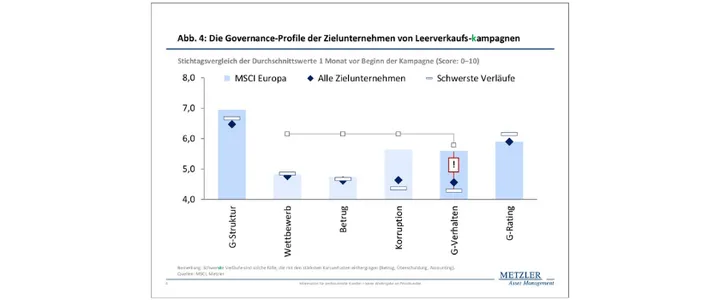
An analysis of all nearly one hundred activist short-selling campaigns that have targeted European publicly traded companies since 2010 reveals two key findings: First, for 90% of the targets, the market capitalization at the start of such a campaign was less than 20 billion EUR. Second, 60% of these campaigns were attributable exclusively to ESG controversies, with the vast majority of cases falling into the governance category. Nearly all target companies had been rated significantly lower in terms of governance performance prior to the campaigns (Fig. 4).
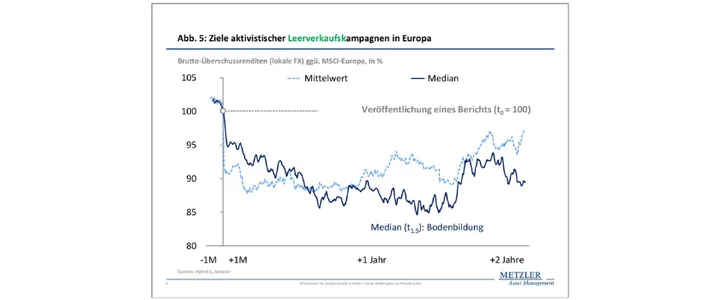
Adjusted for outliers, the gross excess returns of the target companies’ stocks relative to the European stock market fell by 15% (median) until a bottom was reached 18 months after the allegations were made public (Fig. 5). By that point, the market capitalization of the target companies had halved. On an aggregate basis, market capitalization declined by up to 135 billion EUR at its peak.
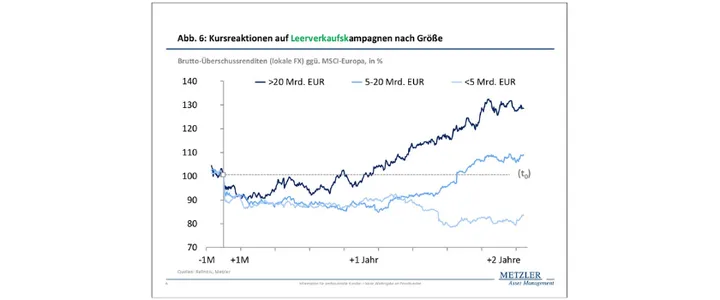
However, unlike large-caps (market capitalization >20 billion EUR) and mid-caps (5–20 billion EUR), the stock prices of small-caps (<5 billion EUR), which accounted for 60% of all target companies, no longer recovered within two years of a short-selling campaign (Fig. 6).
Conclusion: Adherence to governance codes and a more defensive business model can reduce the risk of becoming the target of a short-selling campaign
Nearly all target companies of activist short-selling campaigns in Europe had a poor rating in terms of governance practices. The majority were growth stocks from cyclical sectors, with above-average stock price volatility and high P/E ratios relative to the broader market. Most of these stocks were also rated “buy” by the consensus of financial analysts.
Applied to the SME sector, two recommendations can be derived from this:
Compliance with corporate governance codes, as well as leading expertise in managing risks related to competitive behavior, ethical principles, and corruption, are essential for benefiting from attractive refinancing terms.
A more defensive business model can reduce the risk of becoming the target of activist short-selling campaigns. Specifically, this means investing in projects that promote long-term, organic revenue growth, thereby laying the foundation for a stable profit profile. At the same time, the debt-to-equity ratio should not exceed the optimal level that minimizes the cost of capital.
Footnotes
1 Governance structure describes the nature of four aspects: the supervisory board, ownership structure, compensation structure, and accounting practices. Governance behavior quantifies business practices with regard to susceptibility to corruption and anti-competitive behavior, taxation, and—in the case of financial stocks—additional aspects of financial market stability.
2 Calculation methodology for long-short portfolios: The investment universe is divided into five equal-sized groups (quintiles) based on governance scores. We invest in the quintile with the highest governance scores (Q1), while shorting the quintile with the lowest governance scores (Q5: We obtain the inverse return from this portfolio). The calculations are reweighted on a monthly basis (gross returns in euros).
3 This is because the inverse of the valuation multiple—for example, the price-to-earnings ratio, or P/E ratio for short (1/P/E)—can be expressed as a yield in percent. It follows that a P/E ratio of 20x (1/20 = 5%) is more advantageous for refinancing than a P/E ratio of 10x (1/10 = 10%).
4 In activist short-selling campaigns, short selling of stocks is used to speculate on falling prices before reports are published claiming that a target company is overvalued. If the borrowed securities can be repurchased at a lower price, a profit equal to the difference between the purchase and sale prices, minus the borrowing fee, is recognized.


